
Ten years ago, buying a house meant weekends of open houses, a stack of paper at the bank, and a long afternoon around a conference table signing your name a hundred times. Today you can tour a Brooklyn co-op from a laptop in Albany, upload your pay stubs from your phone, and sign most of your closing documents on a screen. That’s real progress. It also creates new ways to get it wrong, from trusting a 3D walkthrough that hides a water stain to wiring your down payment to a scammer. This guide walks through what actually changed in the buyer’s journey, where the new tools help, and where you still need to slow down and check things the old-fashioned way.
1. The first showing now happens on a screen
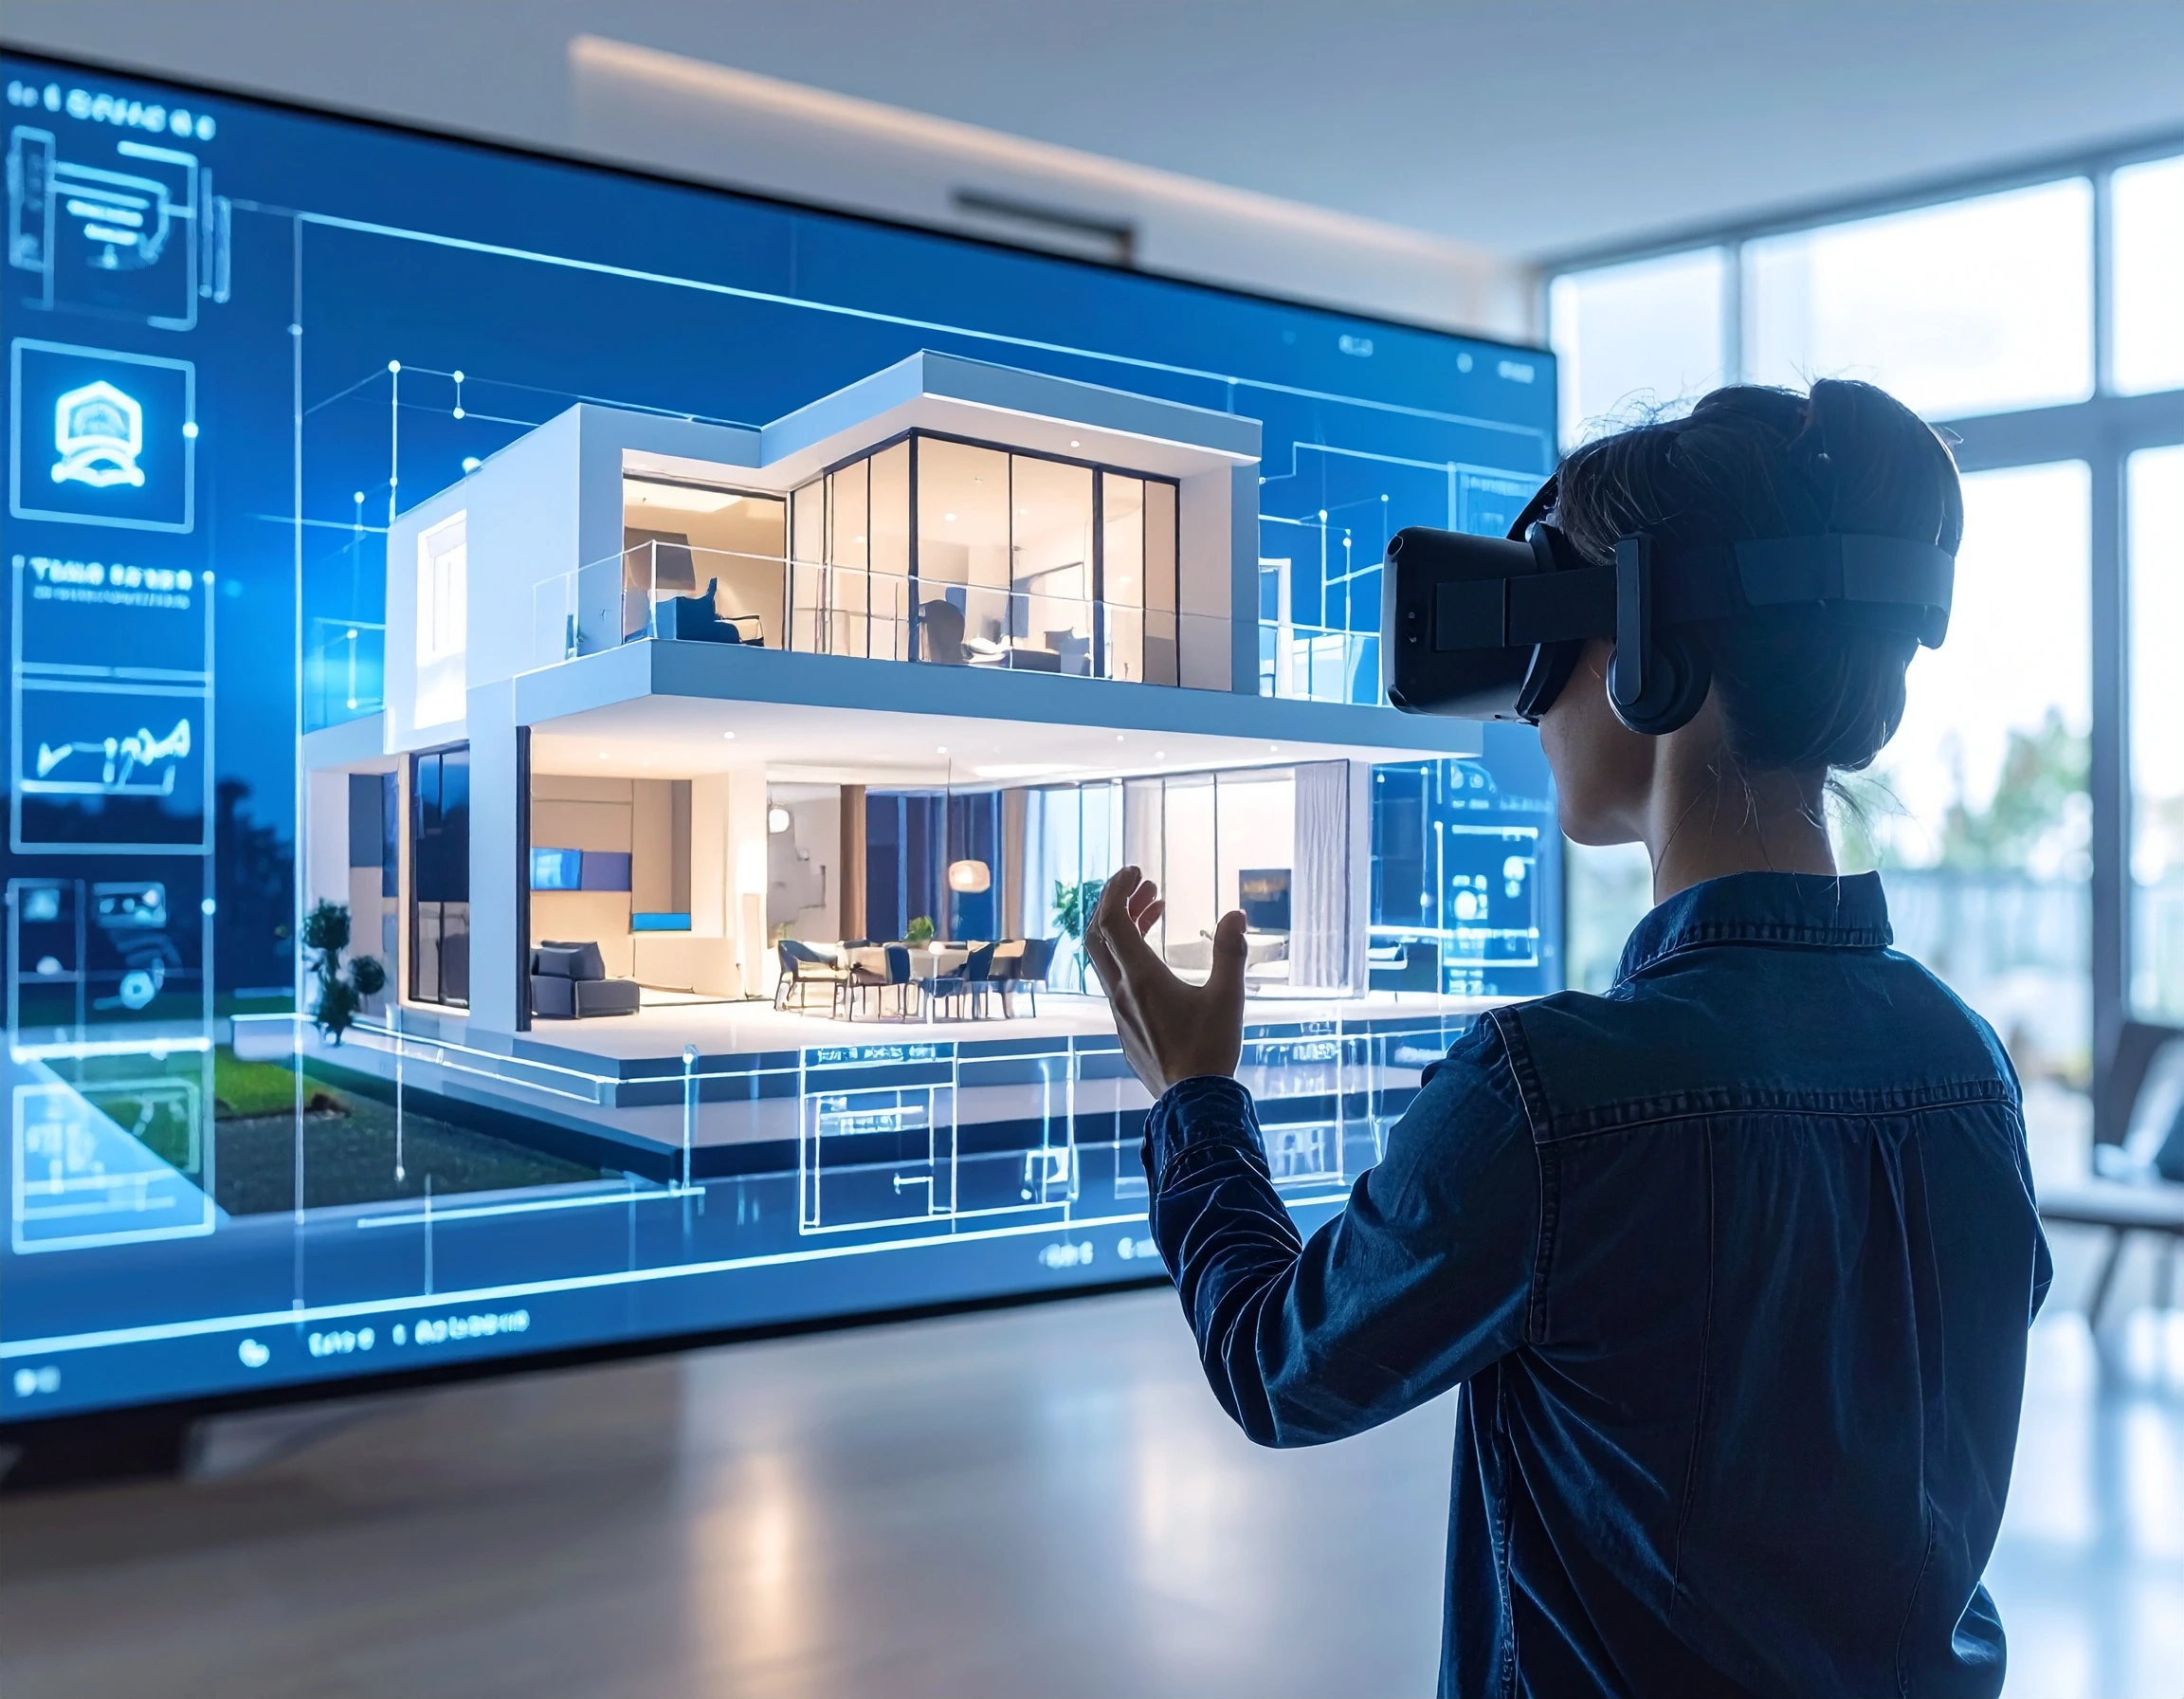
Virtual tours went from a novelty to a standard listing feature in just a few years. Most listings now come with a 3D walkthrough, a floor plan you can click through, or at least a video tour. Many agents will also run a live video showing over FaceTime or Zoom if you can’t get there in person.
For buyers, the upside is obvious. You can rule out a place in ten minutes instead of losing a Saturday to it. If you’re relocating from out of state, or comparing apartments in Queens and Westchester at the same time, a virtual first pass saves serious time and gas money.
The limits matter just as much. A 3D camera captures what’s in front of it, and the seller decides when to shoot. It won’t show you:
- The smell of mildew in the basement or cigarette smoke in the carpet
- Street noise from a bus route or a bar on the corner at 11 p.m.
- Soft spots in the floor, sticky windows, or a furnace that rattles
- How much light the rooms really get at the time of day you’ll be home
Wide-angle lenses also make small rooms look bigger, and staging software can add furniture that was never there. Use the virtual tour to build your shortlist, then see the finalists in person or send someone you trust. And no matter how good the tour looked, don’t skip the professional home inspection. A tour shows you the house the seller wants you to see; an inspector shows you the one you’re actually buying.
2. Applying for a mortgage without visiting a branch
The mortgage application moved online faster than almost any other step. Most lenders, from big banks to online-only companies, now let you apply through a web portal or an app. You link your bank accounts, upload tax returns and pay stubs, and get a preapproval letter back, sometimes within the same day.
That speed helps in a competitive market, where sellers often won’t look at an offer without a preapproval attached. It also makes it easier to shop around. Getting quotes from three or four lenders used to mean three or four meetings. Now it’s a few evenings of paperwork, and comparing loan estimates side by side can save you real money over the life of the loan.
A few habits make the online process work better:
- Compare the official Loan Estimate forms, not the headline rates in ads. The standardized form shows fees, points and closing costs in the same layout for every lender.
- Keep your documents in one folder before you start. Lenders ask for the same things: two years of tax returns, recent pay stubs, bank statements, and ID.
- Know who your human contact is. Even app-first lenders assign a loan officer or processor. Get their direct phone number early; you’ll want it when an underwriter asks a question three days before closing.
Behind the scenes, this shift is part of a broader change in how brokers, lenders and title companies run their businesses. For a wider look at where the industry is heading, this overview of real estate technology trends from Glorium Technologies covers some of the tools reshaping the transaction from the industry side. As a buyer, you don’t need to understand the software. You just need to know which steps are automated and which still depend on a person reviewing your file.
3. AI valuations: a useful starting point, not a price tag
Every listing site now shows an estimated value next to the asking price. Zillow’s Zestimate is the best-known version, but Redfin, Realtor.com and many banks run their own automated valuation models, or AVMs. These models use public records, recent sales, tax data and listing details to estimate what a home is worth.
They’re handy for getting a feel for a neighborhood. They’re much less reliable for a specific house. Zillow publishes its own accuracy figures, and they tell a clear story: for homes currently listed for sale, its median error has run around 2%, but for off-market homes it has hovered around 7%. The gap exists because once a home is listed, the model can see the asking price and adjust toward it. For a house nobody is selling, it’s working from older and thinner data.
A 7% median error means half of off-market estimates miss by more than that. On a $600,000 house, that’s a swing of $42,000 or more in either direction. In New York, where a renovated townhouse and an untouched one on the same block can sell for very different prices, an algorithm that can’t see inside either one will struggle.
Here’s how to use AVMs sensibly:
- As a buyer, treat the estimate as one data point. Ask your agent for a comparative market analysis built from recent nearby sales, and look at the actual sale prices yourself.
- As a seller, don’t set your price based on the number a website shows. An agent who walks through your home will catch the new kitchen or the old roof that the model misses.
- For financing, remember that your lender will order its own appraisal (or, in some cases, accept an appraisal waiver based on its own data). That number, not the website’s, decides how much the bank will lend.
4. E-signatures and remote online closings
Closing used to be the most stubbornly paper-based step in the whole process. That changed quickly during the pandemic and has stuck. Today, much of the paperwork can be signed electronically, and in many states the final notarized documents can be handled online too.
There are a few flavors worth knowing:
- E-signatures cover most of the documents along the way: the purchase agreement, disclosures, and many lender forms. These are legally binding under federal and state e-signature laws.
- Hybrid closings let you e-sign most documents ahead of time, then sign only the few that need a notary in person, often in a much shorter meeting.
- Remote online notarization (RON) lets a notary verify your identity and witness your signature over a live video call, with the session recorded.
Whether RON is available to you depends on your state, and on whether your lender, title company and county clerk accept it. New York made remote online notarization permanent under Executive Law Section 135-c, which took effect on January 31, 2023, after the temporary pandemic-era rules expired. Notaries who want to perform remote notarizations in New York have to register with the Department of State as electronic notaries. New Jersey, Connecticut and many other states have their own rules, so if you’re buying across state lines, ask your attorney or title company which method they’ll use.
In New York, there’s one more factor: attorneys handle most residential closings here, and many still prefer to meet in person for the final signing, especially on co-ops. Don’t assume a fully remote closing is an option. Ask early, so you can plan travel or arrange a power of attorney if you won’t be in town.
5. Wire fraud: the risk that came with digital closings
Here’s the part of digital home buying nobody likes to talk about. When so much of the deal runs through email, criminals have learned to insert themselves into the conversation. The classic scheme is simple. A scammer hacks or spoofs an email account belonging to your agent, attorney or title company, watches the thread, and then sends you “updated” wiring instructions right before closing. You send your down payment, and it’s gone.
The numbers are getting worse, not better. According to the FBI’s Internet Crime Complaint Center, criminals stole more than $275 million through real estate-related fraud from at least 12,368 victims in 2025, up from about $173 million and 9,359 complaints the year before. The broader category that powers many of these schemes, business email compromise, cost victims $2.77 billion in 2024 alone, according to the FBI’s 2024 Internet Crime Report.
The fixes are low-tech, and they work:
- Confirm wiring instructions by phone, using a number you already have from your contract or from the company’s official website. Never use a phone number from the email that contains the instructions.
- Treat any last-minute change as a red flag. Legitimate title companies almost never switch bank accounts days before closing.
- Call to confirm receipt right after you send the wire, so any problem gets caught within hours, not days.
- If something goes wrong, act immediately. Call your bank to request a recall, then file a report at ic3.gov. Speed matters; the sooner the bank knows, the better the chance of freezing the funds.
6. A practical checklist for a mostly digital home purchase
Put all of this together and the modern buyer’s journey looks something like this. You browse listings and take virtual tours to build a shortlist. You get preapproved online and compare lenders. You visit the finalists in person, make an offer, and hire an inspector. You sign most documents electronically, and you close either in person, in a hybrid meeting, or fully online, depending on your state and your attorney.
At each stage, one question keeps you safe: what would I have checked if this were on paper and in person? You’d have walked the house, so walk it. You’d have looked a lender in the eye, so get your loan officer on the phone. You’d have handed a cashier’s check to someone you recognized, so verify every wire by calling a number you trust.
Technology removed a lot of the friction from buying a home. It didn’t remove the need for judgment. The buyers who come out ahead are the ones who use the new tools for speed and the old habits for verification.
The bottom line
The biggest changes in home buying sit in three places: how you first see a home, how you apply for the loan, and how you sign at the end. Use virtual tours to narrow your list, but never to replace an in-person visit and a professional inspection. Read AI valuations as rough estimates, not as the price you should pay or ask. And before any money leaves your account, confirm the wiring instructions with a phone call to a number you already trust. Those three habits will cover most of what can go wrong in a digital deal.

